

Does homeowners insurance cover trampolines?
Updated September 16, 2026 . AmFam Team
A backyard trampoline can be a fun way for kids to stay active and enjoy time outside. But before you bring one home, it’s smart to understand how it could affect your homeowners insurance.
Whether you already have a trampoline or you’re thinking about buying one, here’s what to know about insurance coverage, liability risks, and the steps you can take to help protect your household.
What to know about trampoline insurance coverage
Depending on your policy and insurer, a trampoline may not be automatically covered under your standard homeowners insurance policy.
Many insurance companies view trampolines as a higher-risk feature because they can lead to injuries and liability claims. In some situations, coverage may be available if certain conditions are met, such as:
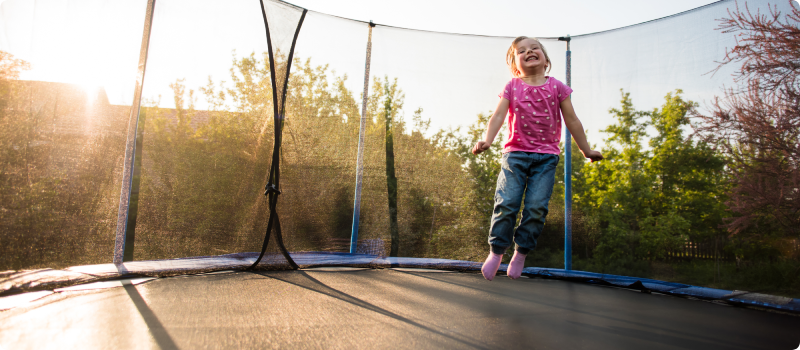
- A safety net around the trampoline
- A fenced yard with a locking gate
- Other safety precautions required by your insurer
Why trampolines can affect your homeowners insurance
Trampolines may increase risk in two key ways:
1. Liability risk
If someone is injured while using your trampoline, you could be responsible for related medical bills, legal expenses, or damages, depending on the situation and your policy.
2. Property risk
You may also wonder whether the trampoline itself would be covered if it’s damaged by a covered loss, such as a windstorm. Whether that protection is available depends on your policy terms and whether your insurer allows coverage for the trampoline as personal property.
The best way to understand your coverage is to talk with your American Family Insurance agent before installing or using a trampoline on your property.
Do I need to tell my insurance company I have a trampoline?
Yes. If you add a trampoline to your property, you should let your insurer or agent know.
This is important for a few reasons:
- You can confirm whether your policy allows trampolines.
- You can find out whether any safety requirements apply.
- You can help avoid coverage or policy issues if your property details are complete and accurate.
Keeping your policy information up to date helps ensure your coverage reflects the risks on your property.
Does a trampoline increase homeowners insurance rates?
It can.
If your insurer allows trampolines, adding one may increase your premium because it can raise the chance of an injury claim. Eligibility and pricing depend on your insurer, your property, and your policy.
In some cases, insurers may require protective measures before they’ll consider coverage. These may be similar to rules for other backyard features, such as a swimming pool, that can increase liability exposure.
What is an “attractive nuisance”?*
A trampoline, pool, or swing set may be considered an attractive nuisance. This term refers to an object, structure, or feature on your property that is inviting, or attractive, to a child, even if they do not have permission to use it.
If a child enters your property and is injured by an attractive nuisance, you, the property owner, could be held legally responsible in some situations. That’s one reason insurers often have strict rules around trampolines and other backyard structures.
Adding reasonable safety measures, like fencing, locked gates, or protective netting, may help reduce risk.
What kind of insurance protection should I consider?
If trampoline coverage is available, you may want to review your liability protection with your agent.
Personal liability coverage
Your homeowners policy includes personal liability coverage up to a certain limit. If you're concerned about injury risks, it may make sense to ask whether your current limit is enough for your situation.
Medical payments or medical expense coverage
Depending on your policy, this coverage may help with certain medical costs if someone is injured on your property, subject to policy terms, conditions, and exclusions.
Personal property coverage
If your policy allows it, personal property coverage may apply to damage to the trampoline itself from a covered loss. Availability varies.
Umbrella insurance
You may also want to consider adding umbrella insurance. Umbrella insurance can provide an added layer of liability protection above the limits of your homeowners policy. This means, if you face a lawsuit that goes beyond your base coverage, your umbrella policy could step in to provide additional liability protection.
Learn more about liability insurance
Connect with an agent for a quote
The bottom line is, many homeowners insurance policies don’t automatically cover trampolines. Some may offer coverage if specific safety conditions are met, while others may exclude trampolines altogether.
If you have a trampoline or are considering one, connect with your American Family agent. They can help you understand your current coverage, explain any policy limitations, and discuss whether additional liability protection may be right for you.
And if you’re in the market for homeowners insurance, let us help! We’ll help you review your options and understand available coverage choices. Contact an agent and get a quote today.
This information represents only a brief description of coverages, is not part of your policy, and is not a promise or guarantee of coverage. If there is any conflict between this information and your policy, the provisions of the policy will prevail. Insurance policy terms and conditions may apply. Exclusions may apply to policies, endorsements, or riders. Coverage may vary by state and may be subject to change. Some products are not available in every state. Please read your policy and contact your agent for assistance.
*This article is for informational purposes only and based on information that is widely available. This information does not and is not intended to constitute legal or financial advice. You should contact a professional for advice specific to your situation.