

What is a named perils policy?
Updated September 18, 2026 . AmFam Team
A named perils policy covers losses caused by specific events listed—or “named”—in your policy. In insurance, those events are called perils.
That means if damage is caused by a peril named in your policy, the loss may be covered. If the loss isn’t listed, it typically isn’t covered.
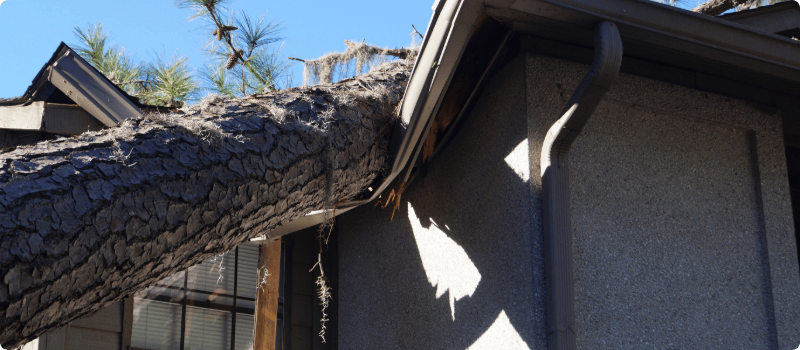
For example, let’s say a sudden kitchen fire damages your stove, cabinets, and flooring. If fire is one of the named perils in your policy, that loss may be covered.
Understanding the difference between named perils and open perils coverage can help you choose protection that fits your home and budget.
Let’s take a closer look.
What does peril mean in insurance?
A peril is a cause of damage or loss. In homeowners insurance, perils may include things like fire, hail, or theft.
With a named perils policy, coverage applies only to the perils specifically listed in the policy.
Common examples of named perils may include:
- Fire or lightning
- Hail or windstorm
- Riot
- Explosion
- Aircraft
- Smoke
- Vehicles
- Falling objects
- Theft
The exact covered perils depend on your policy terms.
How does a named perils policy work?
With a named perils policy, coverage is limited to the specific risks named in the policy. Some homeowners choose named perils coverage when they want a more focused foundation of protection and then add other coverage options based on their needs.
This approach can be helpful if you want to better understand what is covered and tailor your coverage choices.
What is an open perils policy?
An open perils policy works differently. Instead of listing every covered peril, open perils coverage generally covers losses unless the cause of loss is specifically excluded in the policy.
You may also hear open perils coverage called:
- All-risk coverage
- Special perils coverage
- Special form coverage
Because it covers causes of loss, open perils coverage is often considered broader than named perils coverage.
Is open perils coverage always broader?
In many cases, open perils coverage provides broader protection for your home or your personal property than named perils coverage.
But broader coverage doesn’t mean everything is covered.
For example, normal wear and tear is commonly excluded. If an older dishwasher stops working because of age and use, that type of loss generally wouldn’t be covered.
Always review your policy for exclusions, limitations, and conditions.
Can you add coverage for excluded losses?
In some instances, you may be able to add protection through an endorsement, depending on the policy and your state.
For example, certain causes of loss, such as earthquakes, may not be included in a standard homeowners insurance policy. Additional coverage may be available by endorsement where offered.
Keep in mind that adding coverage may increase your premium, but it can also give you extra risk protection.
Which type of policy may be right for you?
The right policy depends on your home, your budget, and the risks you want to prepare for.
When evaluating named perils vs. open perils coverage, consider these questions:
- Is your home in an area with hail, wildfire, or severe storms?
- Do you live near a fault line or in a flood-prone area?
- Do you want broader protection or more targeted coverage?
- Are there specific risks you want to cover through endorsements?
Thinking through these questions can help you more confidently choose coverage that fits your needs.
Talk with an American Family Insurance agent
If you’re comparing named perils and open perils coverage, an American Family Insurance agent can help you understand your options and build a homeowners insurance policy that fits your situation.
Talking through your risks, budget, and coverage goals can help you make a more informed decision about protecting your home.
This information represents only a brief description of coverages, is not part of your policy, and is not a promise or guarantee of coverage. If there is any conflict between this information and your policy, the provisions of the policy will prevail. Insurance policy terms and conditions may apply. Exclusions may apply to policies, endorsements, or riders. Coverage may vary by state and may be subject to change. Some products are not available in every state. Please read your policy and contact your agent for assistance.